myWisely: Mobile Banking
ADP, INC.
- 4.4
- 11.60K Reviews
- 1.00M
- Downloads
- Free
- Price
Screenshots
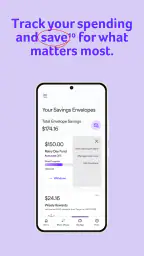
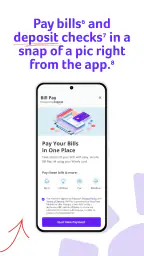
myWisely: Mobile Banking Pros and Cons
Pros
- User-friendly interface
- Instant balance updates
- No monthly fees
- Secure transactions
- Real-time alerts
Cons
- Limited customer support
- No international transfers
- Occasional app crashes
- Limited investment options
- Requires internet access
 Analysis by All-app
When I weigh a finance app, I start with a practical question: does it give me a useful way to manage money I already receive, without charging me to install it? myWisely: Mobile Banking is free to download, so trying it does not involve an upfront purchase. That is a straightforward advantage if you want to explore a mobile account experience before deciding whether it suits your routine. Free access alone, though, does not tell you what every service or transaction may involve, so I would read the terms that apply to your account rather than assume every banking activity is cost-free.
What the free app can—and cannot—settle
I see the strongest value here in convenience: keeping an eye on money coming in and spending going out from a phone, rather than relying only on a desktop banking session or scattered records. ADP, INC. makes this finance app, and its core appeal is captured by the tasks its name points toward: getting paid, tracking spending, and saving. That can be useful when you want a single place to check your day-to-day money, but it should not be mistaken for a promise that the app replaces every feature of a traditional bank.
For a realistic example, imagine payday arrives while you are commuting and you need to decide whether a bill can be paid before the weekend. A quick balance check can help you make a more informed choice than relying on memory. Later, reviewing recent spending may help explain why the available amount feels lower than expected. I find that kind of small, timely check more valuable than an elaborate budget plan that I would forget to maintain.
Where it fits among finance apps
Compared with a conventional bank’s app, a mobile money tool like this is most compelling when its payment and spending routines match the way you receive and use funds. A general-purpose budgeting app may be better for someone who wants to bring several accounts together or build detailed spending reports; a bank app may be the better everyday hub if it already handles all the accounts, transfers, and services that person needs. I would choose based on the actual role myWisely can play in my own setup, not on the assumption that one finance app should do everything.
A useful habit is to treat the app as a check-in point, not as a substitute for a monthly review. I would look at it after pay arrives, then again before a recurring expense is due, and compare what I see with bills that are still pending. That simple routine can make spending decisions less impulsive without requiring constant phone checks. It also keeps the app’s value tied to a concrete task instead of turning money tracking into another notification-driven distraction.
Who is likely to get the most from it
I would consider it if I wanted a phone-first way to keep tabs on incoming pay and everyday spending, and if its account setup suited how I receive money. It may be less useful if I need a broad financial dashboard, rely on features my main bank already provides, or prefer to do all financial planning on a computer. Before moving important routines over, I would check that the account arrangement and available services fit my needs. The app is free, but the time spent changing habits is still a cost, so the practical question is whether it makes a regular task easier.
The app has an average rating of 4.4 from around 29,000 ratings, and it has passed over one million installs. Those figures suggest that many people have tried it, but they do not tell me whether its particular account workflow will suit you. I would use popularity as background, then judge it by whether the balance and spending information is clear and useful in my own day-to-day routine.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Getting Started with myWisely
First things first, setting up myWisely: Mobile Banking is a breeze. Once you've downloaded the app, the user interface is intuitive, almost like it reads your mind. I was able to link my bank account and set up direct deposits without having to consult a manual or spend hours on customer support. Plus, the app's sleek design makes navigating through its features a cool experience.
Features That Make It Stand Out
Let’s talk features. One of my favorites is the real-time balance updates. I don’t know about you, but I love knowing exactly where my finances stand at any moment, and this app delivers just that. It also sends notifications for any suspicious activities, which is a huge relief in this age of digital scams. A unique feature that caught my eye is the money management tool. It’s like having a mini financial advisor in your pocket, helping you budget and plan your expenses smartly.
Another cool aspect is the rewards system. Every time you spend using the app, you get points. Who doesn’t like earning while they spend? It’s like the app is giving you a little pat on the back for every purchase you make.
The User Experience
Using myWisely feels like a conversation with a savvy financial guru who’s got your back. The app’s developers clearly focused on making the user experience seamless. The support section is comprehensive, covering a wide array of questions you might have, and if that’s not enough, their customer service is just a tap away.
I’ve also noticed that the app is light on battery usage, which is a big win. There’s nothing worse than an app that drains your phone’s battery faster than a kid in a candy store.
Final Thoughts
In conclusion, if you're searching for a mobile banking app that’s as smart as it is user-friendly, myWisely: Mobile Banking is a stellar choice. It combines convenience with security, making it a must-have in today’s fast-paced world. Whether you’re tech-savvy or just getting started with digital banking, this app caters to all levels of users with its simple yet powerful features.
So, what are you waiting for? Give myWisely a try and take control of your finances with confidence. Trust me, you’ll wonder how you ever managed without it!
Making the daily balance check more useful
In practice, a balance is only helpful when I understand what it represents in the context of my next few days. I would use a quick check to make a decision, then verify any planned payment against my own bill reminders. That matters because a displayed balance should not automatically be treated as a full forecast of what remains after pending purchases or upcoming obligations. Keeping a separate note of fixed bills can prevent the common mistake of seeing money available and assuming it is all discretionary.
For spending review, I would look for patterns rather than scrutinize every small purchase. A few recurring charges or repeated convenience purchases can explain a tighter week more clearly than a long list of individual transactions. If the app’s money-management view helps surface those patterns, it can support a simple routine: review, identify one adjustment, and move on. I would not expect an app to make the budget decision for me; the useful part is having information close at hand when I choose what to change.
Payday habits and account setup
The most sensible time to assess whether the app fits is before making it central to a payday routine. I would first understand how the account is connected to the way I get paid, then check that the deposit information and balance view make sense. If you are switching from another arrangement, avoid changing every payment at once. Keeping your existing method available while you confirm that incoming pay appears as expected is a cautious transition, especially when rent or other essential bills depend on it.
Direct deposit is particularly relevant for someone who wants pay to arrive in an account they can monitor from a phone. It can simplify checking whether funds have arrived, but it does not remove the need to keep track of payment dates or confirm instructions with an employer or payer. I would make the transition only after I understood what information needs to be submitted and had a plan for any bills due during the changeover. That is less exciting than tapping through setup, but it is the kind of practical step that prevents avoidable stress.
For someone paid on an irregular schedule, the app may be most useful as a visibility tool rather than a budgeting solution by itself. I would compare the money currently available with essential expenses first, then decide what can safely be spent. A simple written list of upcoming bills can complement a phone-based balance check and keep an uncertain pay cycle from turning into guesswork.
Notifications are prompts, not a security plan
Alerts can help me notice activity that deserves a closer look, but I would treat them as an early signal rather than a guarantee that every problem will be caught. If a transaction looks unfamiliar, the sensible response is to open the account, check the details, and use the available support or account controls promptly. I would also avoid acting on a message that asks me to disclose sensitive information; reaching the service through the app itself is a safer habit than following an unexpected prompt.
This is one area where convenience and attention need to be balanced. Too many alerts can become background noise, while ignoring every notification defeats the point of having them. I would keep the alerts that help me spot important account activity and make a habit of checking them at a time when I can respond. That approach makes notifications more useful without treating a phone as a complete substitute for careful account management.
What to check before relying on rewards
Rewards can make everyday spending feel more engaging, but I would not spend extra just to collect them. The value depends on the terms attached to a particular rewards program and on whether its benefits matter to me. My rule would be to make the purchase I already planned, then regard any reward as a bonus rather than a reason to buy. That keeps a points feature from quietly undermining the very spending awareness the app is meant to support.
I would also separate rewards from savings when deciding what the app is doing for my finances. Points are not the same thing as cash set aside for a bill, and a reward should not be included in my budget until I understand how it can be used. If a user mainly wants a disciplined savings plan, a dedicated savings arrangement may be a better fit; if the goal is simply to monitor day-to-day money and engage with spending, rewards may add some appeal.
Compatibility and choosing the right fit
The app is listed for Android devices running version 6.0 or later, and its current version is 25.23.0. It is rated for Everyone, so the age classification is broad, but I would still make sure the account is appropriate for the person using it and that they understand basic financial safety. The app was released on April 30, 2019, which gives useful context for its history without telling me how well it will work on a particular device today.
One question readers often have is whether a mobile finance app can replace their existing bank app. I would not assume so. If you need account services beyond the specific tasks you use here, keep the other app until you have confirmed that your essential routine is covered. The more accounts and bill arrangements you depend on, the more important it is to test one workflow at a time rather than make a full switch based on a promising first impression.
Another practical question is whether it is suitable for someone new to digital banking. Its age rating is Everyone and the interface is described in the original review as approachable, but a first-time user should still take time to understand account details, notifications, and safe sign-in habits. I would start with basic checks and avoid storing passwords in an unsecured place. A friendly layout can reduce friction; it cannot replace knowing how to protect access to an account.
My recommendation
My bottom line is that the free download makes myWisely worth considering if you want a mobile view of pay and everyday spending, and if its account setup matches your circumstances. Its practical value comes from helping you check money at the moments when you need to make a decision, not from promising to solve every financial task. I would try it as a focused tool, keep a clear record of upcoming essentials, and judge it by whether it genuinely makes your routine easier.
I would skip it as a primary solution if your priority is detailed multi-account analysis, a particular service your existing bank already handles better, or a fully hands-off budget that makes decisions for you. For everyone else, the sensible verdict is to consider the free app without assuming that free installation answers every question about account terms. Check how it fits your pay and spending habits, start cautiously, and keep whichever financial tools still do an important job for you.
Frequently Asked Questions
What is myWisely: Mobile Banking and how does it work?
myWisely: Mobile Banking is a financial app designed to help users manage their money efficiently. It offers features like budgeting tools, transaction tracking, and instant notifications for spending. Users can link their bank accounts to view balances, transfer money, and pay bills directly from the app. It's a convenient tool for staying on top of your finances.
Is myWisely: Mobile Banking secure to use?
Yes, myWisely: Mobile Banking prioritizes user security by employing encryption technologies and multi-factor authentication. This ensures that your financial data is protected against unauthorized access. The app also provides fraud alerts and allows you to lock your card instantly if suspicious activity is detected, giving you peace of mind when managing your finances.
Can I use myWisely: Mobile Banking with multiple bank accounts?
Absolutely, myWisely: Mobile Banking supports linking multiple bank accounts, allowing you to manage all your finances in one place. You can view balances, transactions, and even transfer funds between accounts. This feature is particularly useful for users who have several accounts and want a unified view of their financial status.
What fees are associated with using myWisely: Mobile Banking?
myWisely: Mobile Banking is generally free to download and use, but certain transactions may incur fees. For example, withdrawing cash from out-of-network ATMs or using expedited bill pay services might have additional charges. It's advisable to review the app's terms and conditions or contact customer support for detailed information on any potential fees.
How can I get help if I encounter problems with myWisely: Mobile Banking?
If you experience issues while using myWisely: Mobile Banking, the app offers multiple support channels. You can access a comprehensive help center within the app, contact customer service via phone or email, or engage with the community forums for peer advice. This ensures you can find solutions and continue managing your finances without delay.